

Energy Capital Partners eyes generational opportunity as it deploys largest fund yet


- Fund VI closed on USD 8.1bn in August, already closed or agreed three investments
- GP bullish on sustainable infrastructure, environmental services, renewables, nuclear
- Focus on Fund IV realizations, Cornerstone exit delivered early windfall for Fund V
Energy Capital Partners has spent over two decades investing in areas of energy that benefit from long-term demand growth but remain relatively under-capitalized. Now, after raising its largest fund to date, the Summit, New Jersey-headquartered manager sees a generational opportunity for this approach.
“The energy transition, AI [artificial intelligence] infrastructure buildout, and industrial onshoring are creating a multi-decade pipeline of investable platforms, and Fund VI positions ECP to act at the scale these opportunities demand,” Tyler Reeder, the firm’s president and CIO, told this news service.
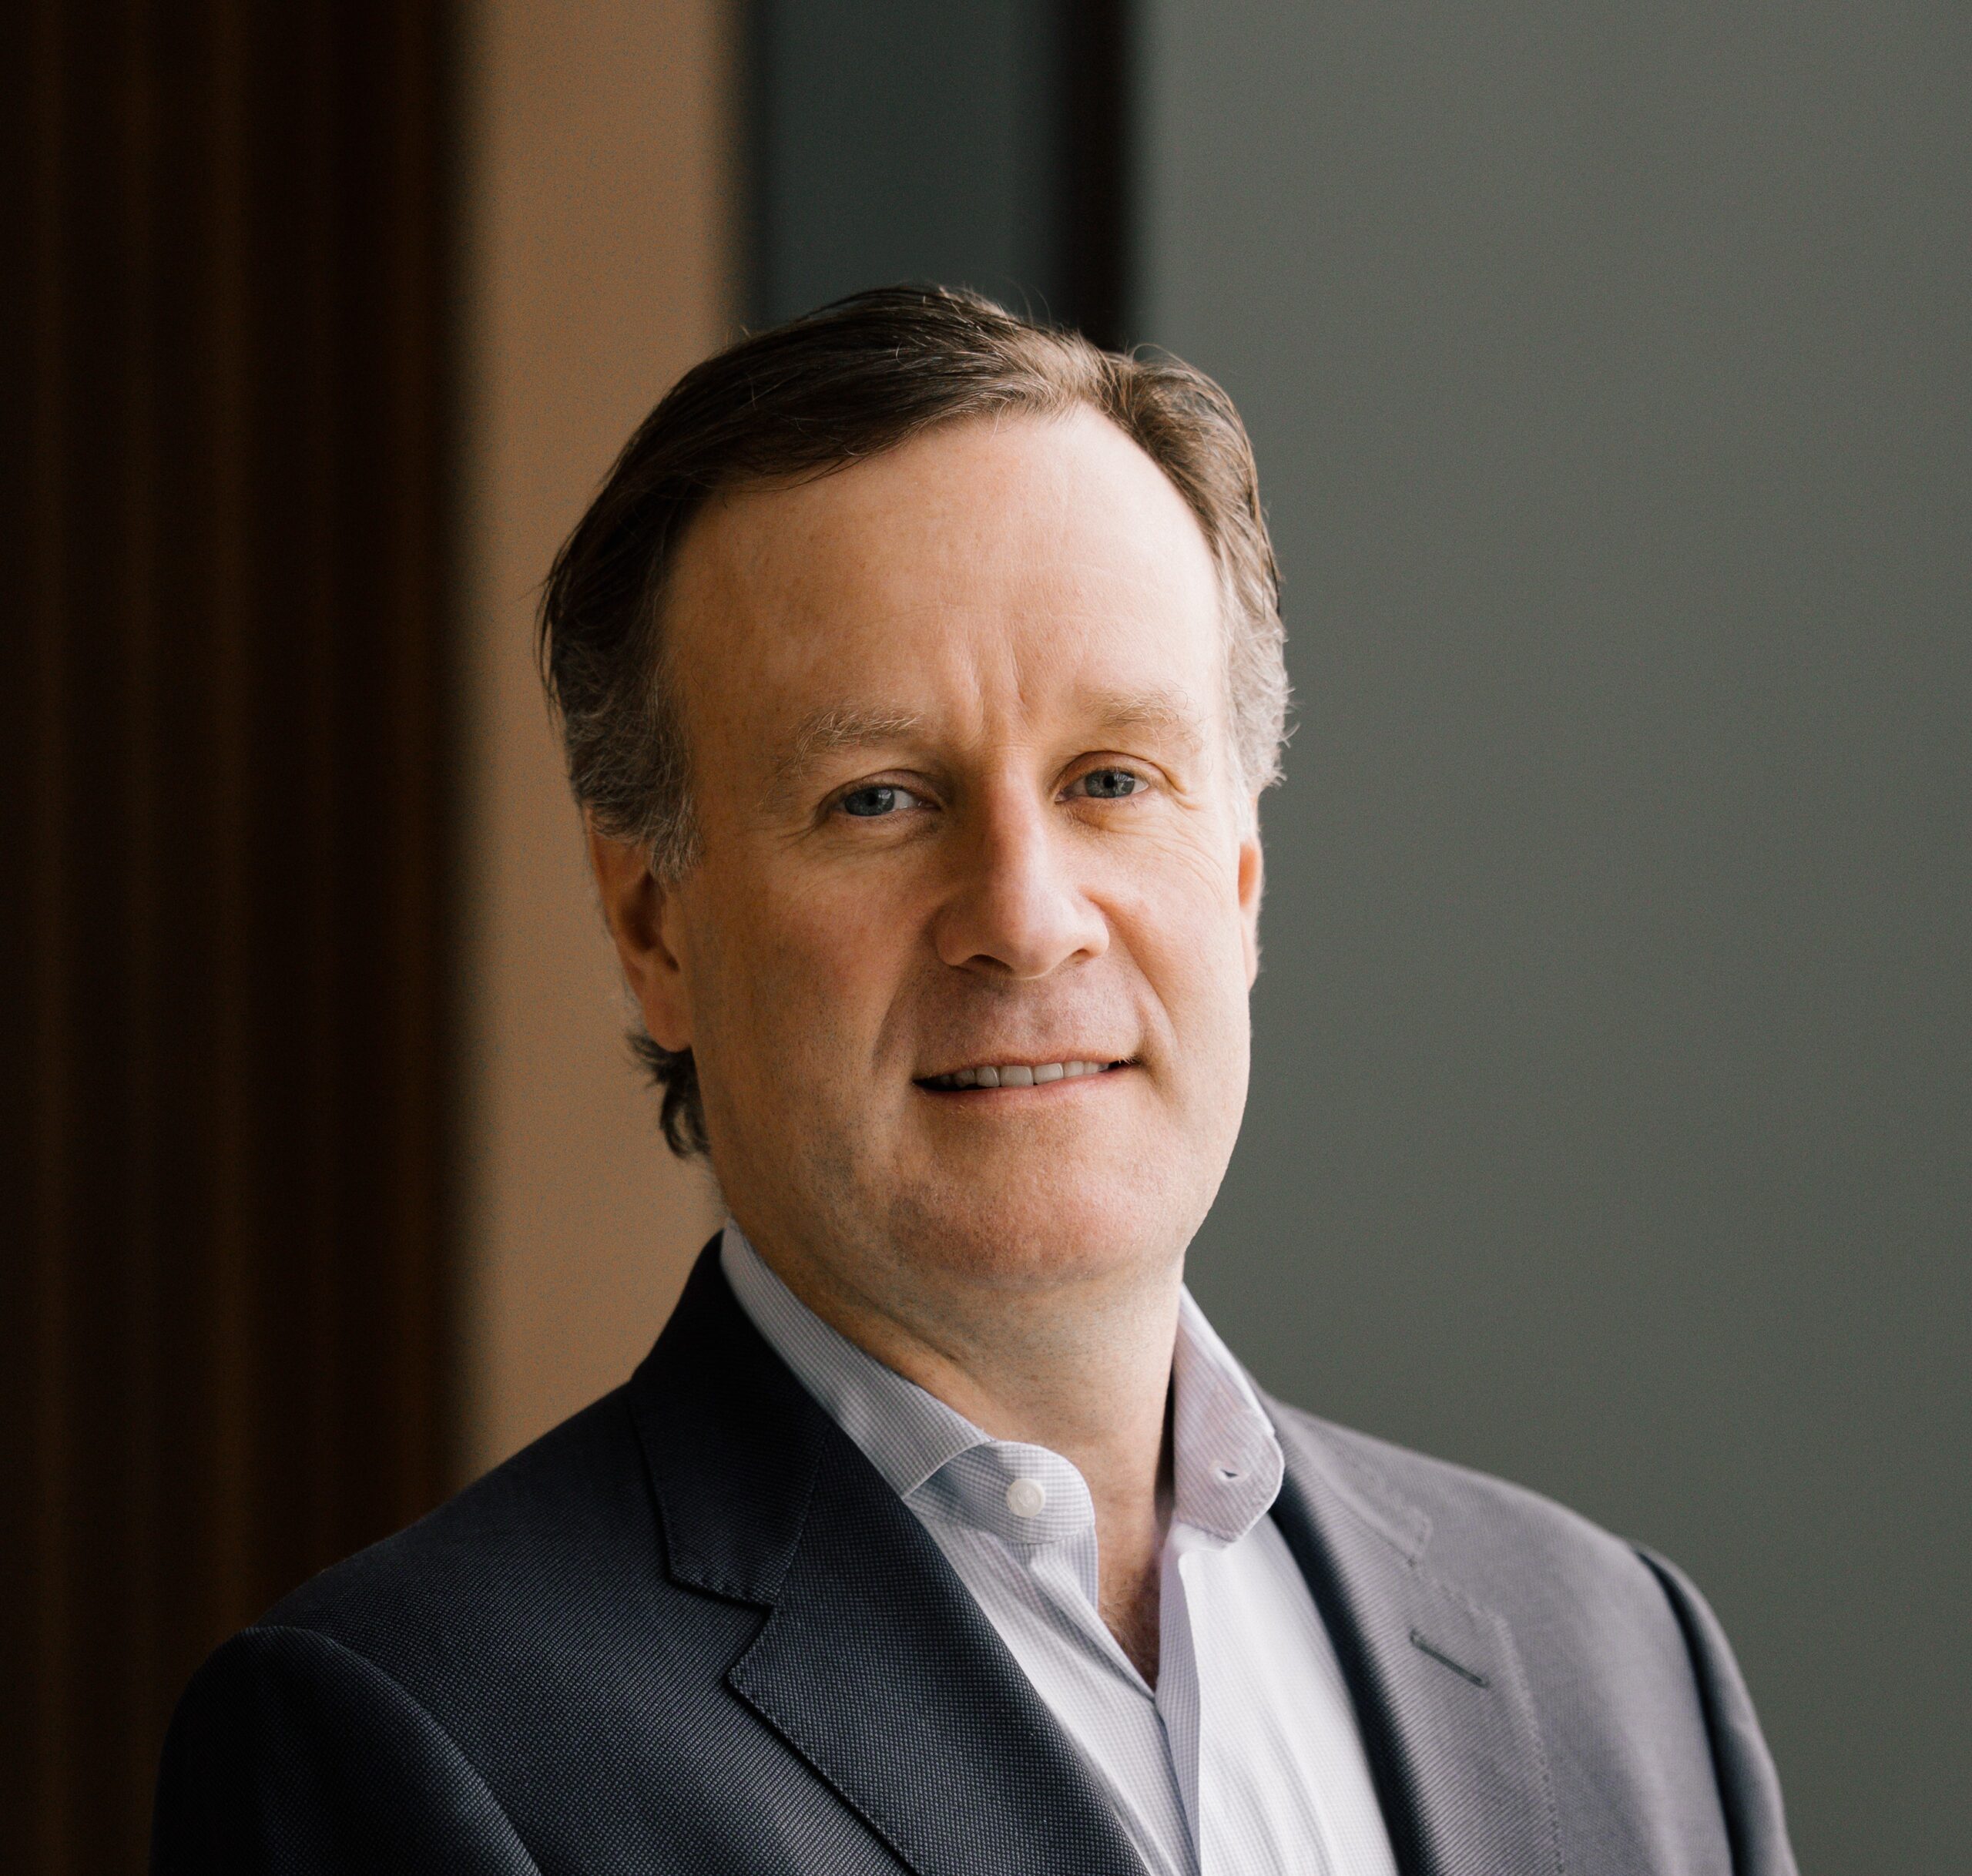
Reeder
ECP’s investors appear to share that view. Fund VI closed last month on USD 8.1bn, well above the initial USD 5bn target, with the hard cap lifted to accommodate the extra demand. The firm also comfortably exceeded the Fund V total of USD 4.4bn.
LPs in the new vintage include sovereign wealth funds, public and private pensions, insurance companies, asset managers and family offices, according to a press release. Infralogic previously reported that Minnesota State Board of Investment, Iowa Public Employees’ Retirement System, and Teacher Retirement System of Texas made commitments of USD 250m, USD 200m and USD 150m.
The fundraise played out amid accelerating deal activity across the energy sector. According to Mergermarket data, North American energy and natural resources M&A has reached USD 401.8bn year-to-date. Utility and power account for nearly 65% of the total, underlining the steady increase in electricity demand – and the mega trend might still be in the early innings.
Having remained nearly flat for 15 years, US electricity consumption has grown by an annual average of just over 2% in the last five years, according to the US Energy Information Administration (EIA). It projects annual expansion of 0.9%-1.6% through 2050, citing data center demand as a key driver.
ECP believes these are ideal conditions for executing its strategy. “We think the opportunity set in certain power markets is outstripping the amount of capital interested in the sector,” Reeder said. “One advantage we’ve had is specialist expertise in a part of the market where there are still relatively few experts.”

Opportunity set
Deployment of Fund VI began last year as ECP teamed up with UK-based energy player Centrica to acquire Grain LNG, Europe’s largest liquefied natural gas terminal, from National Grid for GBP 1.66bn (USD 2.24bn). This was followed in April 2026 by the announced purchase of Utah-based nuclear power business EnergySolutions from TriArtisan Capital Partners.
More recently, ECP and KKR won board approval for a GBP 5.73bn (USD 7.7bn) take-private of Dublin-headquartered energy distributor DCC Energy. The next step is a shareholder vote on the bid.
The fund was 12% deployed as of June 2026, according to Bridgepoint’s 1H26 earnings statement. Bridgepoint, which has more than USD 97bn in assets under management, bought ECP two years ago to add infrastructure to its existing private equity and credit offerings.
Overall strategy for Fund VI remains focused on power generation, renewables and storage, and sustainable infrastructure. The opportunity set extends to companies that support the broader power ecosystem. “We’re looking at businesses that are offshoots of power generation itself, including sustainable infrastructure and environmental services,” Reeder explained.
Equipment manufacturers and service providers are expected to be among the beneficiaries of the structural shift in energy markets. Notable areas of interest include companies that supply critical equipment – such as turbines – which Reeder said are seeing strong demand.
More broadly, ECP has noted plentiful openings in renewables, with Reeder describing the landscape a something of a buyer’s market. “While post-One Big Beautiful Bill, policy changes have cast a shadow, they’ve also made some assets cheaper. For experienced investors, that can create opportunity,” he explained.
Nuclear power is also emerging as another potentially high conviction theme on the back of AI infrastructure-linked power demand and growing energy security concerns. The International Energy Agency (IEA) has described nuclear as entering a new era, supported by rising investment and supportive policies across more than 40 countries.
There is widespread expectation of increased construction activity. Reeder subscribes to this view, predicting “a new wave of nuclear plants.”
Beyond generation assets themselves, the nuclear resurgence presents opportunities to invest in service and infrastructure assets in areas such as decommissioning and waste disposal. ECP’s agreed take-private of EnergySolutions is a case in point.
The company operates disposal and processing facilities and logistics and transportation businesses for low-level radioactive waste used by the majority of US nuclear plants as well as the US Department of Energy, according to ECP’s website. It is active in multiple nuclear plant decommissionings, including Zion Nuclear Power Plant and San Onofre Nuclear Generation Station.
Paths to exit
In addition to putting Fund VI to work, ECP is busy harvesting assets from earlier vintages. One example is Next Wave Energy Partners, a Fund IV investment for which ECP is exploring a continuation vehicle (CV), as previously reported by Mergermarket. Anchor investors have already been signed up for a deal that could be around USD 900m in size, as reported.
Next Wave operates the Project Traveler facility in the Houston Ship Channel, which produces alkylate, a gasoline blending component that helps refiners produce cleaner-burning fuel. The company announced a commitment of up to USD 500m from ECP in April 2015, to be used to develop midstream and downstream assets. However, ECP’s website puts the date of the investment as March 2018.
Should the Next Wave transaction proceed, it would be the private equity firm’s third CV in just over five years, following renewable energy platform Terra-Gen in 2021 and power producer Calpine in 2022. Both businesses were subsequently exited through strategic sales. Terra-Gen was sold to Masdar in 2024 and Calpine was acquired by Constellation Energy for USD 34.1bn, in a deal completed in January 2026.
Other notable recent exits include Liberty Tire Recycling, Symmetry Energy Solutions and Cornerstone Generation, which were sold to I Squared Capital, NextEra Energy Resources, and Talen Energy, respectively.
Liberty Tire was exited after a fairly typical around four-year hold, but Cornerstone – a 2.5 GW natural gas power provider with a portfolio of assets based in the Midwest – was offloaded barely six months after acquisition. The sale was worth USD 3.45bn and based on a 6.6x EBITDA multiple.
Cornerstone delivered a faster-than-expected 6.4x return for Fund V, driving distributions to USD 1.3bn as of June, according to Bridgepoint’s earnings statement. The fund as a whole was marked at a 3.1x money multiple and a 65.4% IRR with distributions to paid-in (DPI) 0.6x. Bridgepoint described the money multiple as “an outstanding achievement for an infrastructure fund.”
Nevertheless, Reeder said that Fund V remains largely in value creation mode. Rather, Fund IV – which raised USD 3.3bn plus an additional USD 3.5bn for co-investment – is the current focal point in terms of generating returns. The 2018-vintage fund was on a 2.1x money multiple and a 20.9% gross IRR as of June. It has already achieved DPI of 1x.
Reeder is confident about the general liquidity outlook, citing a conducive market for exits. “There’s significant capital available, public energy markets have performed well, and we’re seeing strong competitive tension across transaction processes,” he said.
A service of 

Your M&A Future. Today
Explore unlimited content like this, available only in the platform.
Already a client? Sign in